 Bitcoin News
Invesco’s physical bitcoin model outperforms synthetic myths

Physical custody removes swap risks
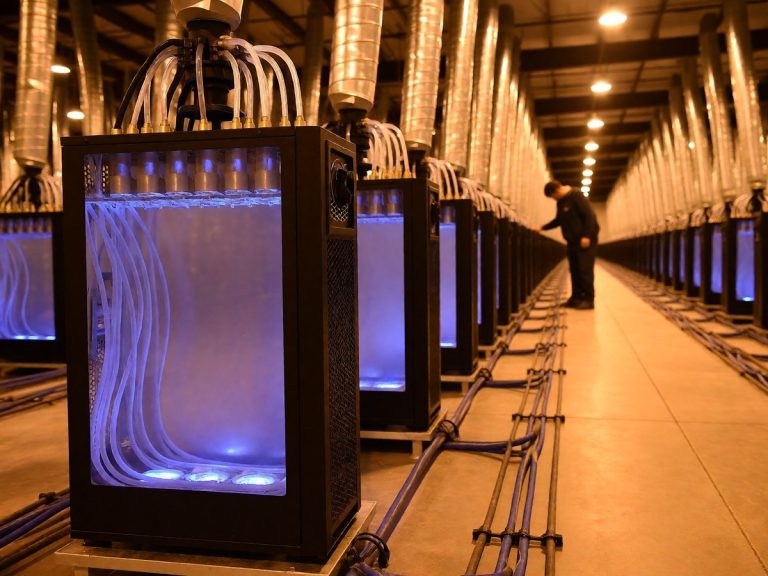
Invesco Galaxy Bitcoin ETF (BTCO) holds physical bitcoin through a custody agreement with Coinbase. Coinbase stores the bitcoin in tamper-proof hardware modules within secure data centers. This physical structure removes the counterparty risk that affects synthetic ETFs. In a synthetic model, a financial institution agrees to pay the return via a swap contract. If that institution defaults, the ETF suffers losses. The Invesco Galaxy Bitcoin ETF utilizes Coinbase to store bitcoin in tamper-proof hardware modules within secure data centers, which removes the difficult operational requirement for investors to manage their own digital wallets or private keys. Galaxy Asset Management acts as the execution agent for the buying and selling of bitcoin. Galaxy oversees $5.3 billion in assets. Invesco manages over $430 billion. For the first six months after the January 11, 2024 launch, Invesco waives the entire sponsor fee on assets up to $5 billion. This waiver brings the 0.25% expense ratio to zero. This partnership combines Invesco’s ETF infrastructure with Galaxy’s experience managing crypto ETPs in Canada, Brazil, and Europe. The fund uses the Lukka Prime Bitcoin Reference Rate to determine fair market value. This rate aligns with GAAP and IFRS guidelines.
Misconceptions about synthetic replication
Synthetic ETFs use derivatives to obtain exposure, which creates a need for collateral. European regulations restrict an ETF’s exposure to any counterparty to a maximum of 10% of its net asset value. While synthetic replication allows access to illiquid markets, physical funds like BTCO provide direct exposure to the market price of bitcoin. This exposure follows the Lukka Prime Bitcoin Reference Rate. Some believe synthetic ETFs provide superior tracking, but physical funds avoid the friction of daily rebalancing and swap counterparty risk. Synthetic providers use different models. Unfunded swaps allow the ETF to hold its own collateral, while funded swaps require a counterparty to post collateral in a segregated account. In funded models, the counterparty uses legal arrangements like a transfer of title or a pledge to ensure collateral is available. A transfer of title means the collateral is the property of the ETF. A pledge means the counterparty holds the collateral for the benefit of the ETF. If a bankruptcy administrator freezes assets in a pledge arrangement, liquidation delays occur. BTCO saw a 39.89% return over the last 90 days. However, the trust’s returns will not match the performance of bitcoin because the trust incurs the Sponsor Fee. The market price of shares may also reflect a discount or premium to the net asset value. You should look at the prospectus to understand these costs. Will regulatory shifts eventually force a transition from physical to synthetic models? Regulatory changes could also alter the nature of an investment in bitcoin.
Market preference for direct exposure
The market favors direct ownership, as U.S. spot Bitcoin ETFs saw $3.2 billion in inflows recently. This capital movement supports funds that buy the underlying asset. BTCO holds $350 million in assets and shows a 30.09% return over the last 60 days. The fund allows trading on the Cboe BZX Exchange. Bitcoin hit a price of $125,930, which shows the volatility of the asset.
| BTCO Metric | Value |
|---|---|
| 90-Day Return | 39.89% |
| 60-Day Return | 30.09% |
| 30-Day Return | 5.77% |
| 7-Day Return | 9.11% |
| 1-Year Return | -23.89% |
| Expense Ratio | 0.25% |
| AUM | $350 million |
BTCO shows 45.97% volatility over the last year. This value stays lower than the 59.97% volatility of the WNTR YieldMax MSTR Short Option Income Strategy ETF. BTCO also shows a lower 6-month volatility of 27.32% compared to WNTR’s 44.57%. The 1-year return for BTCO hit -23.89%, while the 2-year return reached 31.53%. WNTR’s 1-year return reached -31.85% and its current drawdown reached -44.40%, while BTCO’s current drawdown sits at -32.96%.