 Bitcoin News
CleanSpark expands Wyoming capacity to 15 EH/s

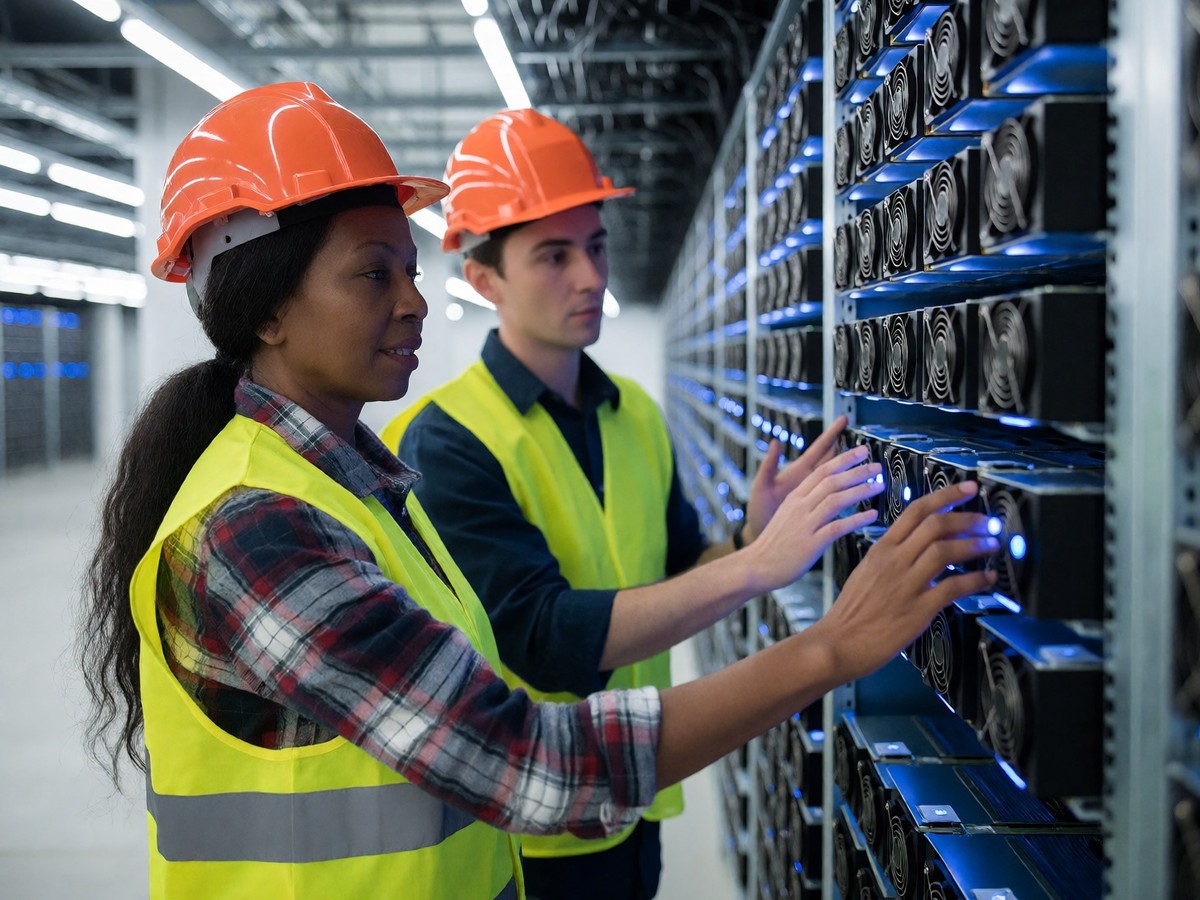
CleanSpark successfully expanded its Wyoming wind farm this month to reach 15 EH/s of capacity. This expansion allows the company to overtake the Nevada output of Core Scientific. CleanSpark controls a portfolio of power, land, and data centers across the United States. The company focuses on monetizing low-cost, high reliability energy by producing compute, which it identifies as a global emerging critical resource.
The company operates at the intersection of Bitcoin, energy, operational excellence, and capital stewardship. I find the rapid scaling of this 15 EH/s capacity to be the most impressive part of the recent development. CleanSpark reported revenue of 138.01M for Q3 2026, though this figure represents a 2.90% decrease compared to the 142.12M estimated for that period. The company also reported a net income of -239.84M for Q3 2026, which follows a net income of -378.34M in the previous quarter.
| Metric | Value |
|---|---|
| Wyoming Capacity | 15 EH/s |
| Q3 2026 Revenue | 138.01M USD |
| Q3 2026 Net Income | -239.84M USD |
| Q2 2026 Revenue | 136.41M USD |
Insider activity and analyst views
Management and directors at CleanSpark engaged in significant buying activity recently. On September 9, 2026, S. Matthew Schultz, the CEO and Chairman, purchased 560.7K shares for 7.07M USD. On the same day, Gary Anthony Vecchiarelli, the President and CFO, bought 241.7K shares for 3.05M USD. Scott Eugene Garrison, the EVP and Chief Development Officer, purchased 164.2K shares for 2.07M USD. Brian Jay Carson, the CAO, bought 93.2K shares for 1.17M USD. Other directors, including Amanda Cavaleri, Larry McNeill, Roger Paul Beydon, and Thomas Leigh Wood, each purchased 7.8K shares for 113.56K USD on September 10, 2026. Taylor Monnig, the CTO and COO, sold 60.2K shares for 776.42K USD and 29.8K shares for 393.43K USD on September 9, 2026.
Analysts maintain a positive outlook on the stock despite the recent net losses. Northland Securities analysts Michael Grondahl and an unnamed colleague both maintain a Buy recommendation with a price target of 21.00 USD, which implies a 47.3% increase. Chad Dillard and Gautam Chuggingani of Bernstein both maintain a Buy recommendation with a price target of 24.00 USD, suggesting a 68.3% rise. Clear Street analysts Brian Dobson and John Todaro maintain a Buy recommendation with price targets of 22.00 USD and 23.00 USD, respectively.
| Analyst | Firm | Recommendation | Price Target |
|---|---|---|---|
| Michael Grondahl | Northland Securities | Buy | $21.00 |
| Chad Dillard | Bernstein | Buy | $24.00 |
| Brian Dobson | Clear Street | Buy | $22.00 |
| John Todaro | Needham | Buy | $23.00 |
Infrastructure and market position
CleanSpark builds data centers using globally competitive energy prices to optimize infrastructure for shareholder returns. The company positions itself to prosper by producing compute through low-cost energy. During the H.C. Wainwright 28th Annual Global Investment Conference on September 14, 2026, S. Matthew Schultz participated in a panel titled "Powering the AI Boom & Bitcoin Network: The Digital Infrastructure Companies Leading the Charge." This panel included Russell Cann, the Chief Development Officer of Core Scientific, Inc., and Fred Thiel, the Chairman and CEO of MARA Holdings, Inc.
The company faces a difficult fiscal reality regarding its earnings per share. For Q3 2026, the normalized EPS stood at -0.39, which missed the -0.33 estimate by 16.34%. This follows a Q2 2026 normalized EPS of -0.49, missing the -0.23 estimate by 114.91%. I see the massive gap between the company’s revenue growth goals and its actual net income as a major concern.
| Fiscal Period | Revenue | Revenue Surprise | Normalized EPS |
|---|---|---|---|
| Q3 2026 | 138.01M | -2.90% | -0.39 |
| Q2 2026 | 136.41M | -2.50% | -0.49 |
| Q1 2026 | 181.18M | -3.49% | -1.32 |
| Q4 2025 | 223.65M | -1.39% | 0.16 |
Will the 15 EH/s expansion in Wyoming eventually stabilize the net profit margin? CleanSpark’s net profit margin for Q3 2026 reached -173.79%, which is a decline from the -209.02% margin reported in Q2 2025. The company continues to scale its operations even as it reports significant quarterly losses.