 Bitcoin News
Swan Bitcoin’s retirement IRA vs. Fidelity’s FBTC 401k integration

ETF inflow volatility and Fidelity performance
Fidelity’s Wise Origin Bitcoin Fund (FBTC) reached $1.062 billion in total inflows by its fifth day of trading. BlackRock’s iShares Bitcoin Trust led the category with $1.2 billion in inflows. On October 21, 2026, FBTC took in $212.7 million according to CoinLab data. This inflow nearly matched the $526.7 million drawn by all US spot bitcoin ETFs on that same Wednesday. These inflows occurred after a period of volatility where US spot bitcoin ETFs recorded $485 million in net outflows on October 7. That single day of outflows pushed the month’s combined flows into a net loss of $163 million. Grayscale saw much larger movements, with $2.2 billion in outflows on the fifth day of trading. I see these massive fluctuations in ETF capital as a sign of inconsistent institutional interest. The data from October shows that while some days see half-billion-dollar inflows, others see massive withdrawals. BlackRock’s iShares Bitcoin Trust drew $235.0 million on October 21, while Ark Invest/21Shares’ ARKB saw $320.9 million in total inflows since trading began. Invesco’s BTCO saw $194.9 million in inflows, and Bitwise’s BITB fund saw $395.5 million in inflows. FBTC also saw $50.7 million in net outflows in early October amid broader selling across Bitcoin ETFs. A claim on social media suggested Fidelity sold $197.09 million in Bitcoin, but this figure was actually close to the $197.4 million in net inflows for the week ended July 11, 2026. Arkham Intelligence clarified that transfers involving 3,568 BTC, worth approximately $297 million, were internal operations within Fidelity Custody, not sales.
The 401(k) fee transparency dispute
Fidelity faces legal challenges regarding how it handles 401(k) fees. Lawsuits claim the company charges an infrastructure fee to access its 401(k) clients through third-party mutual funds. Fidelity claims the fee does not relate to 401(k) services and stays below 0.05% of a product provider’s assets. However, legal experts argue this fee represents indirect compensation that must be disclosed to satisfy ERISA transparency requirements. When final 408(b)(2) regulations were released in 2012, they sought to improve transparency for 401(k) provider fees. I find the attempt to hide these costs through technical footnotes problematic for business owners who have a fiduciary responsibility. If a provider obscures the true cost of an investment, it makes an apples-to-apples comparison difficult. For example, a John Hancock 401(k) plan with $2,113,454.88 in assets pays 0.42% in JH fees and 0.55% in other fees. This amounts to $20,500.51 in total fees, or $2,050.05 per participant annually. The SECURE Act 2.0 also requires participants earning over $150,000 in W-2 wages to designate catch-up contributions as Roth in 2026. This rule adds another layer of complexity to retirement planning.
Swan Bitcoin’s specialized IRA tools
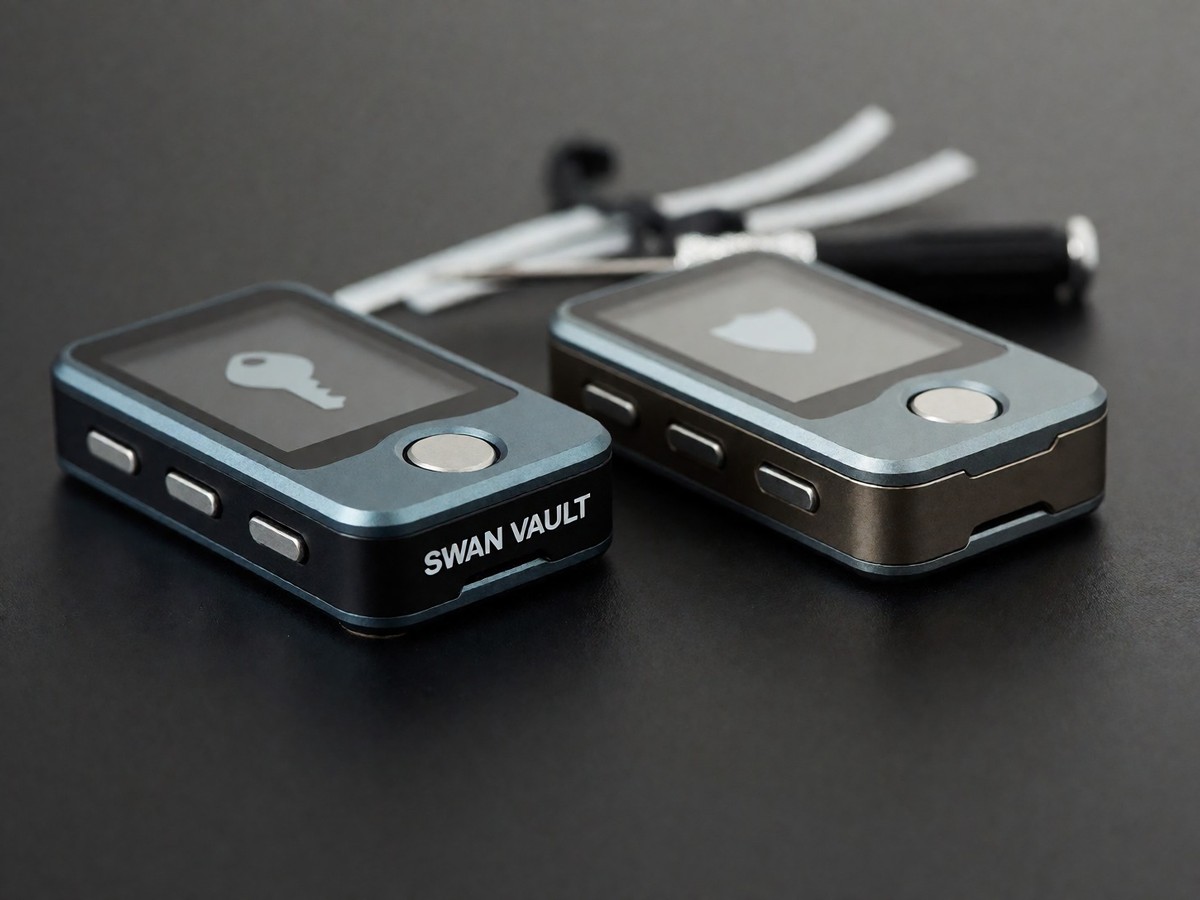
Swan Bitcoin provides a specialized alternative for investors seeking to accumulate Bitcoin through automated recurring purchases. The platform integrates with Equity Trust to provide Traditional and Roth IRAs, SEP IRAs, SIMPLE IRAs, and Solo 401(k)s. Swan Bitcoin uses a multi-key security model called Swan Vault. This system uses two Jade sign-in devices to authenticate ownership, which requires a $159 setup fee. A third Cloud key is managed by Swan. Users can pay $20 per month for unlimited support with any Swan Vault issues.
| Feature | Swan Bitcoin IRA | Fidelity FBTC ETF |
|---|---|---|
| Transaction Fee | 0% on first $10,000; 0.99% after | N/A |
| Monthly/Annual Fee | 0.02% AOP (min $20) | 0.15% to 0.25% |
| Asset Type | Direct Bitcoin | Bitcoin price exposure |
| Minimum Balance | $0 | N/A |
Swan Bitcoin charges $0 in transaction fees for the first $10,000 in Bitcoin purchases. Once a user reaches that $10,000 threshold, the transaction fee is 0.99%. For accounts with more than $100,000, the monthly maintenance fee is 0.02% of the account value, with a maximum of $416.67. This is a significant difference compared to BitcoinIRA, which has transaction fees that can reach 2%. You should consider these math-driven advantages if you plan to dollar-cost average over many years. I think the simplicity of Swan wins for people who only want Bitcoin. Other platforms like Alto offer 200+ cryptocurrencies, and iTrustCapital allows for gold and silver investments. Unchained uses a tiered fee structure, starting at 1.00% for trades up to $100,000 and decreasing to 0.50% for trades between $1 million and $5 million. Swan is available in the U.S., Puerto Rico, Guam, and the Virgin islands, but it is not available in New York, New Jersey, South Dakota, or North Carolina.
Choosing between institutions and autonomy
Fidelity allows retirement account participants to add Bitcoin to their plans, but US senators have criticized this decision. Senators Elizabeth Warren, Richard Durbin, and Tina Smith sent a letter to Fidelity’s CEO questioning why the company exposes retirees to a volatile and illiquid asset. They noted that the median 401(k) balance is only $33,472, while the average balance is $129,157. For those seeking direct ownership of the asset, Swan Bitcoin provides an industry-first IRA structure that includes direct on-chain visibility. This feature allows clients to use a specific watch address to monitor IRA transactions and balances on-chain. I believe Swan Bitcoin is the superior choice for long-term Bitcoin savers because of its low fee structure and single-asset focus. A 2022 Nasdaq survey of 500 financial advisors found that 72% want to invest in Bitcoin and the broader cryptocurrency sector if a Bitcoin spot ETF gets approved. Fidelity provides ease of use through its massive institutional network, while Swan provides precision through specialized Bitcoin tools. The divergence between the two platforms shows the difference between institutional convenience and individual sovereignty. Does the convenience of an established provider outweigh the higher complexity and potential for hidden fees in a 401(k) plan?